





Credit Scores Part 2: Getting a Mortgage with a Low Credit Score
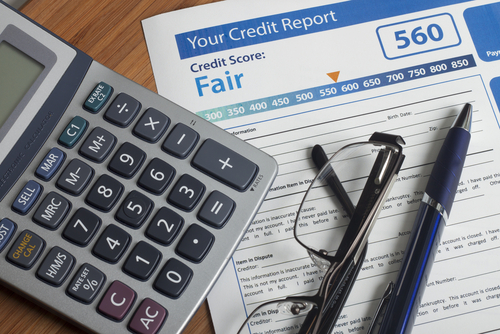 Understandably, banks and building societies are careful who they lend money to, and financial histories are always looked into, with no exceptions.
Looking into a credit history will show up any defaulted payments and give the lender a good impression of how financially responsible you are with your spending. As well as looking at your credit report, lenders will also look at any County Court Judgements (CCJs) or bankruptcy proceedings that may be against your name.
If any of these apply to you, then you may find it harder to be accepted for a mortgage, however, there are certain lenders who will still lend to you.
 The first few months in a new house can sometimes be tough, financially. No doubt you’ve just worked really hard to save enough money to afford to move house or buy for the first time, and now not only are you getting used to your new mortgage repayments and household bills, but you may also need money to redecorate and make the house your own.